Loading video…
All breakouts
14.3Talking HeadWarning hookFinance
Hook
Don't waste time saving up a bigger downpayment
@nateloans
50.6K followers · usually 4.2K views a post
Views
57.2K
Likes
982
Comments
72
Shares
197
Why it worked
The video effectively debunks a common misconception about home buying, providing practical financial advice that resonates with first-time homebuyers. The clear explanation and relatable scenario make the information easily digestible and actionable.
Summary
This video explains that saving for a larger down payment on a house is often unnecessary and can delay homeownership. The speaker, a loan officer, advises that lower down payment options are available and that saving a large sum for a bigger down payment yields minimal monthly savings, while potentially increasing the home's overall cost over time.
Structure
- 1Introduction to the misconception about down payments
- 2Explaining low down payment options (3-3.5%)
- 3Comparing 5% vs 10% down payments and the minimal savings
Original caption
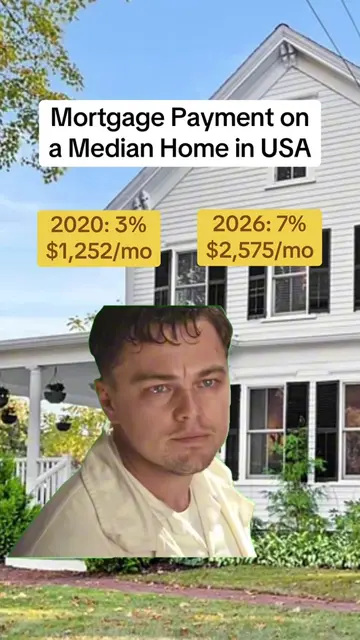
Saving up a bigger downpayment can take years and makes a minimal impact on your mortgage payment. Even if you put an extra hundred thousand dollars down your payment would only drop by around $600 which isn’t the best paying for your buck. All you need to put down on a conventional loan is 3% or 3.5% with FHA, and a lot of times it’s a smarter idea to put the minimum down even if you have more money available so you can keep it as a rainy day fun. Do you want to review your options with me with the L.I.N.K in my bio to schedule a FREE 15 minute call. . . . ##mortgage##mortgagetips##downpayment##firsttimehomebuyer
More from @nateloans
More breakout videos from this creator.