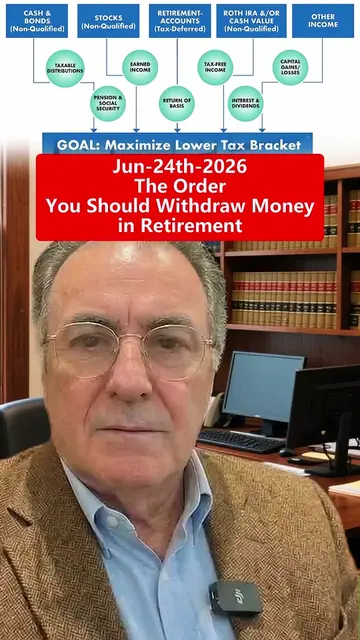
You pulled $20,000 from your 401(k). Just 20. So why is the IRS taxing you like you pulled out $37,000? That gap is no accident, friend. It is a trap. And here is the part that should make you sit up straight. That trap has almost nothing to do with how much money you have saved. It has everything to do with the order you turn your income on. You could have done everything right, saved for 30 years, paid off the house, lived below your means, and still walk straight into it, simply because you flipped the wrong switch first. Get that order wrong and you can hand the government tens of thousands of dollars you never had to part with. Now, most folks your age are sitting on three different paychecks waiting in retirement. There is your 401(k) or traditional IRA, there is Social Security, and for some of you, there is a pension. They all feel like income, but here is the thing: they do not play by the same rules, not even close. One of them you control completely. One of them you can speed up or slow down, and one of them just turns on whether you like it or not. Mix them in the wrong sequence and they work against each other. That is exactly where good people get burned, not because they did not save enough, but because nobody ever told them the order mattered. Before I show you the right order, do me one quick favor. If you are the kind of person who would rather keep your money than donate it to the IRS by accident, go ahead and tap that like button and subscribe so these retirement breakdowns keep finding you. That one click tells YouTube to show this to another retiree who needs it. All right, let us get into it. Let me set the table fast. Bucket 1, your 401(k) or traditional IRA. Every dollar you pull comes out taxed as ordinary income, just like a paycheck from work, because you never paid tax on that money going in. The good news, this is your most flexible lever. Once you are past 59 and a half, you decide when and how much. Required withdrawals, the RMDs, do not force your hand until age 73. Bucket 2, Social Security. You can switch it on as early as 62, but you lock in a benefit cut of about 30% for life. Wait until 70 and your check grows by roughly 8% every year you hold off, about 77% more than the early number. Now here is what most people never realize. Social Security is not taxed based on how big your check is. It is your other income that decides how much of it gets taxed. Read that twice, folks. Your other income decides. Bucket 3, your pension. Fewer people have these anymore, but if you do, it is usually a fixed check that switches on automatically when you retire or at 65. You rarely get to delay it, and it is taxable as ordinary income. So a pension quietly fills up your taxable income floor before you touch anything else. So what do most good, careful people do? They take the sequence that feels safe. They claim Social Security early because it feels guaranteed. They let the 401(k) sit and grow because somebody told them never to touch it, and the pension turns on whenever it turns on. Sounds responsible, does not it? And here is the uncomfortable truth: that safe-sounding order is exactly what springs three tax traps that can cost you a small fortune. Stay with me, because once you see these three traps, the right order becomes obvious. Trap number one is the big one. I call it the Social Security tax torpedo. The IRS uses a special number called your combined income, that is your adjusted gross income plus any tax-exempt interest plus half of your Social Security. As that number climbs past certain lines, more of your Social Security gets dragged onto your tax return. For a married couple, once combined income passes $32,000, up to half your benefit becomes taxable. Past $44,000, up to 85% of it can be taxed. For singles, those lines are $25,000 and $34,000.