Loading video…
Sound

original sound - shyam.vyas
Shyam Vyas · Original audio
0:00–:––
Playing this video’s own audio, so you’ll hear the creator over the sound.
We didn’t find a product being promoted in this video. Its hook, format and structure below still show why it took off.
Browse products winning on TikTokThe video provides high-value, data-driven financial analysis that addresses a specific, timely market event, building authority and trust with the audience.
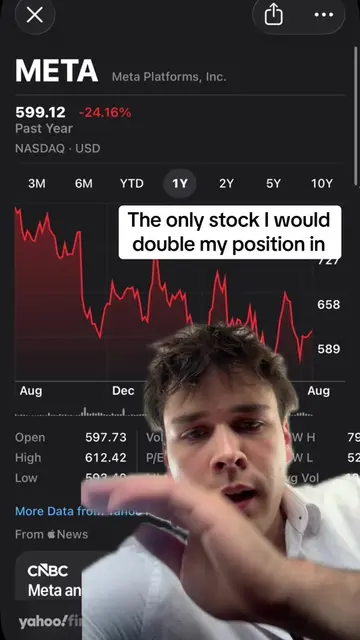
The creator analyzes the recent 25% drop in Meta stock, arguing that the company's core business remains strong despite concerns over high capital expenditure on AI. He concludes that the current valuation presents an attractive risk-to-reward opportunity for long-term investors.
Why Meta stock is down 25% and if it’s a good buying opportunity. For me it’s the most attractive Mag 7 stock at current valuations. #investingtips #stockmarkettips #stockstobuy #investing
Why Meta stock is down 25%
Introduction to Meta's stock performance
Analysis of core business metrics
Explanation of the sell-off due to CapEx
Comparison of valuation against the S&P 500
Discussion of risks and future outlook
Make sure to give this a like and give me a follow if you found this video helpful and to keep up to date on any finance or investing videos that I make.
Playing this video’s own audio, so you’ll hear the creator over the sound.
Outliers and viral hits: their videos on Overshot, all time.