Loading video…
Sound

original sound - 5minutes.finance
5 MINUTES FINANCE · Original audio
0:00–:––
Playing this video’s own audio, so you’ll hear the creator over the sound.
Hook
Posted Jul 26, 2026Video · 3:21by @5minutes.finance
We didn’t find a product being promoted in this video. Its hook, format and structure below still show why it took off.
Browse products winning on TikTokThe video tackles a highly relevant and often debated topic in personal finance, using data and historical context to challenge conventional wisdom. It presents complex financial information in an accessible way, making it shareable for those interested in retirement planning.
This video discusses the 4% rule for retirement withdrawals and presents research suggesting higher withdrawal rates may be sustainable. It highlights studies showing that a 7% withdrawal rate has a high success rate historically, though it acknowledges the risks involved. The video contrasts the traditional 4% rule with newer findings and emphasizes the importance of personalized financial planning.
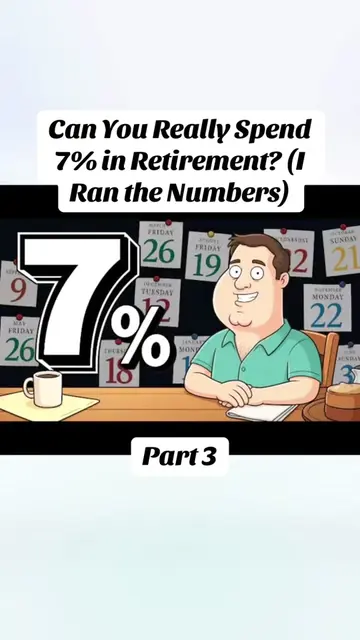
P.2 Can You Really Spend 7% in Retirement? (I Ran the Numbers) #finance #financetok #money #economy #investing
Can You Really Spend 7% in Retirement? (I Ran the Numbers)
Introduction to the 4% rule and its limitations.
Presentation of updated research suggesting higher safe withdrawal rates.
Analysis of historical data and the Trinity study.
Discussion of the risks associated with higher withdrawal rates.
Conclusion on the importance of personalized financial planning.
Playing this video’s own audio, so you’ll hear the creator over the sound.
Outliers and viral hits: their videos on Overshot, all time.