Debt Efficiency Method
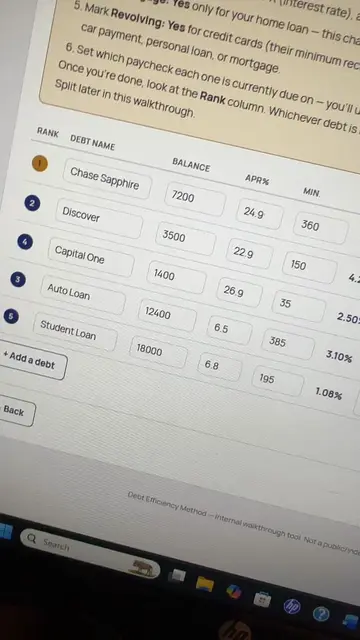
YOUR MINIMUM PAYMENTS ARE WINNING. NOT YOU.Every payday, your minimums take their cut before you decide anything. What's left barely covers you — let alone gets you ahead. The Debt Efficiency Method exists for one reason: to put more of your own money back in your hands every month. For some people that means fully debt-free. For others, it means finally having breathing room that isn't there right now. Either way, it's more cash available to you, month over month.Most people see a real, noticeable shift in what's actually available to them within 3 months or less — not the 3–5 years Snowball or Avalanche can take before your budget feels any different. Just having any real system in place already raises your odds of getting out of debt by roughly 20%. This method goes further — it's built entirely around removing the specific things that cause debt payoff to stall out. Work this method consistently, and the odds are dramatically more in your favor.I'm not asking you to take that on faith. I paid off $160,000 across 14 credit cards using this exact method. My wife and I are running the same system right now against $140,000 in student loans and then $220,000 mortgage... and it's working just the same. Getting started takes about 24 minutes, and you don't need everything ready to begin — just your actual debts. Every number saves the moment you type it, so you can stop anytime and pick up exactly where you left off next payday, next week, whenever.What's inside: 📘 The Guide — the method explained, before you touch a calculator 💳 The Debt Organizer — list your debts, ranked automatically in the order you need to pay them off 📅 The Bill Smoother — fixes bills piling onto one half of the month and balances them through the month automatically, with a call script to move them to other dates 🧮 The Budget — four buckets in, one Margin number out ⚙️ The Complete System — tells you exactly what to do with your margin to consistently build savings and eliminate debt to fr