My Story: I Failed at This for 2 Years Before Paying Off $160K. Full story above — free guide + calculator in bio. #debtfree #debtpayoff #Budgeting #PersonalFinance #creditcarddebt
More from @debtefficiency
More breakout videos from this creator.
The video resonates with viewers by sharing a personal success story and offering a practical, data-driven solution to a common financial problem. The creator's relatable struggle and the promise of a free tool to simplify debt payoff likely drive engagement and sharing.
Summary
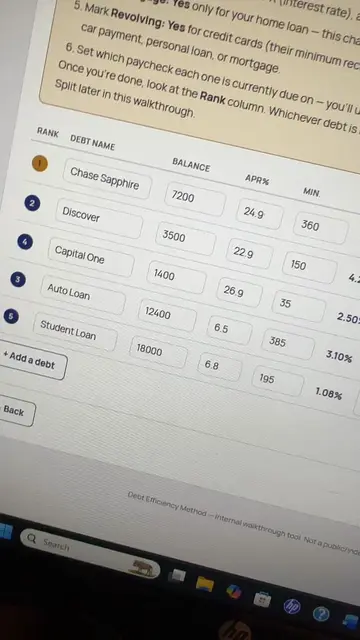
The creator shares his personal story of struggling with debt, explaining how he paid off $160,000 in four years. He highlights a different method for debt payoff than the commonly known snowball or avalanche methods, focusing on attacking the debt that is most costly in terms of interest and cash flow impact.
Structure
1Introduction and personal debt story
2Explanation of common debt payoff methods (snowball/avalanche)
3Critique of common methods and introduction of a new metric
4Demonstration of the new method's effectiveness
5Promotion of a free tool and community for debt payoff
Call to action
Free plan below
On-screen text
My Story: I Failed at This for 2 Years Before Paying Off $160K
HEY, I'M DEREK.
I'M THE CREATOR
EFFICIENCY METHOD.
A BIT ABOUT
ME. I HAD
DEBT LIKE EVERYBODY ELSE
A MORTGAGE, TWO
CAR PAYMENTS,
STUDENT LOANS AND
A FEW CREDIT CARDS.
BUT THE DEBT
DRASTICALLY INCREASED
DURING A PERIOD
OF ME ATTEMPTING
TO REMODEL A
A HOUSE THAT
I HAVE
AS QUICKLY AS
POSSIBLE. I DROVE
THE DEBT ON
TO ABOUT A
HUNDRED AND SIXTY
THOUSAND DOLLARS
ACROSS 14 DIFFERENT
CARDS.
HUNDRED AND SIXTY
THOUSAND DOLLARS.
ENDED UP. SO
EVERYBODY ELSE TELLS
YOU TO DO.
THE FASTEST WAY
DEBT OFF.
CAME DOWN TO
LIKE TWO ANSWERS.
I COULD CHOOSE
THE SNOWBALL,
YOU KNOW, PAY
BALANCE FIRST,
GET A QUICK
WIN, BUILD SOME MOMENTUM
AND THEN YOU'VE
GOT THE AVALANCHE METHOD.
PAYING HIGHEST INTEREST RATE FIRST
MONEY OVER TIME.
BOTH. AND HERE'S
YOU ABOUT EITHER.
1. ALRIGHT.
YOUR BUDGET DOESN'T
FEEL ANY DIFFERENT
UNTIL ALL THAT
DEBT IS COMPLETELY GONE.
IF YOUR PAYOFF
PERIOD IS THREE
YEARS AWAY,
YOU'RE NOT GONNA
THAT BUDGET FOR
THREE YEARS.
YOU JUST KEEP
DOING THE MATH,
KEEP MAKING MINIMUM
KEEP WATCHING YOUR
CASH FLOW
SAY EXACTLY AS
ALWAYS BEEN.
I DID THIS
WATCHING EVENTS WIPE
DOLLAR BABY STEP.
A FEW TIMES
A FEW TIMES
BACK TO DEBT
REST. IT.
ALWAYS THAT WAY.
PAYING CONSISTENTLY STRESS
OVER HOW TIGHT
MY BUDGET WAS
AND HOW TIGHT
MY PAYCHECKS WERE
EACH TIME MAKING
UNNEEDED SACRIFICES.
IT JUST DIDN'T
WORK. NOT BECAUSE
I DIDN'T TRY
HARD ENOUGH.
BECAUSE NEITHER METHOD
WAS ACTUALLY BUILT
AROUND THE THING
THAT I NEEDED MOST,
WHICH WAS ROOM
TO BREATHE IN
MY BUDGET.
AND NOW, NOT
EVENTUALLY BUILT AROUND
HOW LIFE ACTUALLY WORKS
NOT MAKE BELIEVE,
MOMENTUM,
PROBLEM.
THAT HUNDRED AND
SIXTY THOUSAND DOLLARS
IN FOUR YEARS,
STARTING WITH ABOUT
$200 LEFT OVER
OF FAILING, THEN
FOUR YEARS OF SUCCESS.
SO I STARTED
CARDS DIFFERENTLY.
NOT BY BALANCE,
NOT BY INTEREST RATE,
BY ONE NUMBER.
PAYING EVERY SINGLE
MONTH DIVIDED BY
WHAT I OWED?
MINIMUM PAYMENT DIVIDED
BY THE BALANCE.
THAT NUMBER TELLS
YOU SOMETHING THE
OTHER TWO METHODS DON'T
IT TELLS YOU
WHICH CARD IS
ACTUALLY SQUEEZING YOUR
MONTHLY CASH FLOW
RIGHT NOW, REGARDLESS
THE BIGGEST BALANCE,
SMALLEST OR WORST
INTEREST RATES.
AND WHEN I
14 CARDS BY
THAT NUMBER INSTEAD,
THE ORDER WASN'T
ANYTHING LIKE I EXPECTED.
IT WASN'T LIKE
THE SNOWBALL OR
THE AVALANCHE WOULD
TO DO.
THE CAR THAT
WAS ACTUALLY HURTING
ME THE MOST
WASN'T THE BIGGEST ONE,
IT WASN'T THE
HIGHEST RATE ONE.
IT WAS THE
WOULD HAVE PAID
OFF LAST UNDER
THE POPULAR METHODS,
I ATTACKED THAT
CARD FIRST.
AND HERE'S THE
THING. I DIDN'T
WAIT TILL YEARS
TO FILL IT.
MY MINIMUM PAYMENT
DROPPED NOTICEABLY THE
NEXT MONTH,
NOT WHEN EVERYTHING
WAS PAID OFF
THE NEXT MONTH.
WHOLE UNLOCK.
NOT A BUDGET,
NOT CUTTING MY LIFESTYLE
NOT A SIDE
HUSTLE, JUST.
JUST ATTACKING THE
RIGHT ORDER.
THE ORDER THAT
ACTUALLY FREES UP
THE FASTEST,
NOT THE ORDER
THAT FEELS GOOD
OR THE ORDER
THAT MATHEMATICALLY OPTIMIZES
YOUR INTEREST,
IS HOW YOU
ACTUALLY LIVE. $160,000
IN CARS, GONE.
HERE'S WHAT PEOPLE
DON'T TELL YOU. ENOUGH.
I'M NOT DONE.
I ARE RUNNING
THIS EXACT SAME
SYSTEM RIGHT NOW.
AGAINST $140,000 IN
STUDENT LOANS AFTER
FOUR DEGREES BETWEEN US
A MORTGAGE, TWO
CAR PAYMENTS.
METHOD, SAME RANKING,
SAME ATTACK. THE
ONE THAT ACTUALLY
COST YOU THE MOST,
THAT FEELS LIKE
IT SHOULD.
THIS ISN'T A
GUY WHO FIXED
HIS LIFE ONCE
YOU SOME STORY.
I'M USING THIS
RIGHT NOW ON
REAL DEAD IN
MY OWN HOUSE TODAY.
TOOL THAT DOES
THIS AUTOMATICALLY FOR YOU
IT RANKS EVERY
TELLS YOU EXACTLY
WHICH ONE TO ATTACK,
SHOWS YOU HOW
BILLS ACROSS THE MONTH,
HOW TO BUDGET
RIGHT WAY,
AND WALKS YOU
THROUGH THE WHOLE THING
NOT BECAUSE I
A PRODUCT,
BECAUSE I BUILT
IT FOR MYSELF FIRST.
AND THEN I
REALISED THE NUMBER
OF PEOPLE STUCK
WAS WAS ENORMOUS.
AND MOST OF
HEARD THAT THERE'S
A THIRD OPTION
BEYOND SNOWBALL AND
AVALANCHE.
IT'S FREE. FULL
FULL TOOL, NO
CATCH.
BIO. AND IF
YOU WANNA GO DEEPER,
COMMUNITY AROUND THIS TO
LIVE COACHING AND
ALL. ALSO FREE
FREE TO JOIN.
YOU NEED A BETTER BUDGET.
YOU NEED TO
KNOW EXACTLY WHICH
OFF FIRST
AND WHICH ONE'S
ACTUALLY COSTING YOU
THE MOST.
THAT'S IT. THAT'S
THE WHOLE THING.
Transcript
Hey, I'm Derek. I'm the creator of the Debt Efficiency Method. A bit about me. I had debt like everybody else. A mortgage, two car payments, student loans and a few credit cards. But the debt drastically increased during a period of me attempting to remodel a house that I have as quickly as possible. I drove the debt on the credit cards to about a hundred and sixty thousand dollars across 14 different cards. Hundred and sixty thousand dollars. Ended up. So everybody else tells you to do. I looked up the fastest way to pay this debt off. Came down to like two answers. I could choose the snowball, you know, pay balance first, get a quick win, build some momentum, and then you've got the avalanche method. Paying highest interest rate first, money over time. Both. And here's what nobody tells you about either. One. Alright. Your budget doesn't feel any different until all that debt is completely gone. If your payoff period is three years away, you're not gonna that budget for three years. You just keep doing the math, keep making minimum, keep watching your cash flow say exactly as always been. I did this watching events wipe dollar baby step. A few times, a few times back to debt rest. It. Always that way. Paying consistently stress over how tight my budget was and how tight my paychecks were each time making unneeded sacrifices. It just didn't work. Not because I didn't try hard enough. Because neither method was actually built around the thing that I needed most, which was room to breathe in my budget. And now, not eventually built around how life actually works, not make believe, momentum, problem. That hundred and sixty thousand dollars in four years, starting with about $200 left over of failing, then four years of success. So I started cards differently. Not by balance, not by interest rate, by one number. Paying every single month divided by what I owed? Minimum payment divided by the balance. That number tells you something the other two methods don't. It tells you which card is actually squeezing your monthly cash flow right now, regardless the biggest balance, smallest or worst interest rates. And when I 14 cards by that number instead, the order wasn't anything like I expected. It wasn't like the snowball or the avalanche would to do. The car that was actually hurting me the most wasn't the biggest one, it wasn't the highest rate one. It was the one that I probably would have paid off last under the popular methods. I attacked that card first. And here's the thing. I didn't wait till years to fill it. My minimum payment dropped noticeably the next month, not when everything was paid off the next month. Whole unlock. Not a budget, not cutting my lifestyle, not a side hustle, just. Just attacking the right order. The order that actually frees up the fastest, not the order that feels good or the order that mathematically optimizes your interest, is how you actually live. $160,000 in cars, gone. Here's what people don't tell you. Enough. I'm not done. I are running this exact same system right now. Against $140,000 in student loans after four degrees between us, a mortgage, two car payments. Method, same ranking, same attack. The one that actually cost you the most, that feels like it should. This isn't a guy who fixed his life once, you some story. I'm using this right now on real debt in my own house today. Tool that does this automatically for you. It ranks every tells you exactly which one to attack, shows you how bills across the month, how to budget right way, and walks you through the whole thing. Not because I a product, because I built it for myself first. And then I realised the number of people stuck was was enormous. And most of heard that there's a third option beyond snowball and avalanche. It's free. Full full tool, no catch. Bio. And if you wanna go deeper, community around this to live coaching and all. Also free free to join. You need a better budget. You need to know exactly which off first and which one's actually costing you the most. That's it. That's the whole thing.