Loading video…
Sound

original sound - tradex_labs
tradex_labs · Original audio
0:00–:––
Playing this video’s own audio, so you’ll hear the creator over the sound.
Hook
Posted Sep 8, 2026Video · 1:27by @tradex_labs
The video effectively builds trust by showcasing a high win rate, demonstrating a rigorous backtesting and validation process, and providing proof of payouts. The clear explanation of the strategy's performance, especially its shallow losing periods, makes it appealing for prop firm traders.
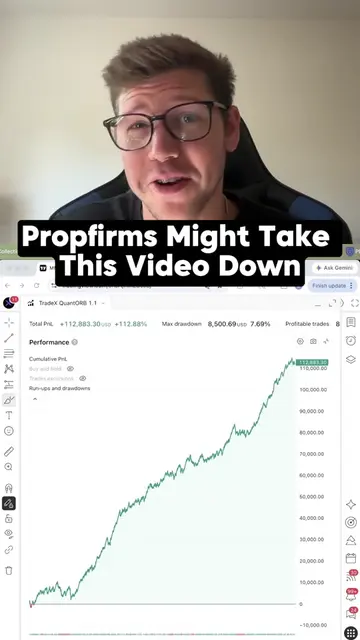
The creator demonstrates a trading strategy called "TradeX QuantORB" that achieved an 80% win rate over 2270 trades in a backtest. They explain the process of parameter optimization, walk-forward validation, and stress testing, showcasing positive results and payouts to validate the strategy's effectiveness, particularly for prop firms.
A backtest by itself means almost nothing. You can make an equity curve look incredible if you optimize enough s*** on the same historical data. The real question is: does the strategy survive when you statistically try to break it? That’s what we did with ORB. We used walk-forward optimization: optimize in-sample, lock the parameters, then test them on the next unseen out-of-sample period. Then roll everything forward and repeat. And before some empiricist comes in here screaming “DATA MINING BIAS” 😂 Yes, we thought about that too. This isn’t a strategy with 47 indicators and 100 parameters that we tortured until something worked. The ORB framework is intentionally simple with relatively few degrees of freedom. More importantly, we weren’t searching for one magical parameter combination. We wanted stability across neighboring configurations and different walk-forward windows. And that’s what we found. The strategy passed across the entire OOS% / walk-forward-run grid tested rather than surviving in one lucky pocket. The majority of rolling OOS windows were profitable, and no single period generated more than half of the total profit. That helps us attack: Curve fitting → repeatedly test unseen data. Look-ahead → lock parameters before the next chronological OOS period. Data mining → limit degrees of freedom and look for broad stability instead of one perfect result. Lucky-period dependence → make sure one abnormal period isn't responsible for the strategy. Then comes the test no statistical validation can replace: Run the d*** thing live. Because none of this guarantees future profitability. We eventually deployed these systems ourselves, have successfully received prop-firm payouts with them, and have had members receive payouts as well. That’s the entire point. If you want to see the multiple ORB variations and the data behind them - visit the link in our bio!
This Backtest Shows an 80% winrate over 2270 Trades for the Past 5 Years
Introduction of backtest results
Explanation of the strategy and optimization process
Validation through walk-forward and stress testing
Demonstration of live data and payouts
Explanation of trade execution and risk/reward
Call to action to visit the link in bio
TradeX QuantORB (ACTS - its interface is operated to backtest a trading strategy, and the results are shown; removing it would change what happens in the video) QuantX Studio (ACTS - its interface is operated to optimize parameters for a trading strategy; removing it would change what happens in the video) TradingView (APPEARS - a corner watermark, removing it would not change what happens in the video)
Visit link in bio!
Playing this video’s own audio, so you’ll hear the creator over the sound.
Outliers and viral hits: their videos on Overshot, all time.
Quantitative trading system for prop firm traders
All time.