Loading video…
All breakouts
21.2Text-HeavySocial Proof hookFinance
Hook
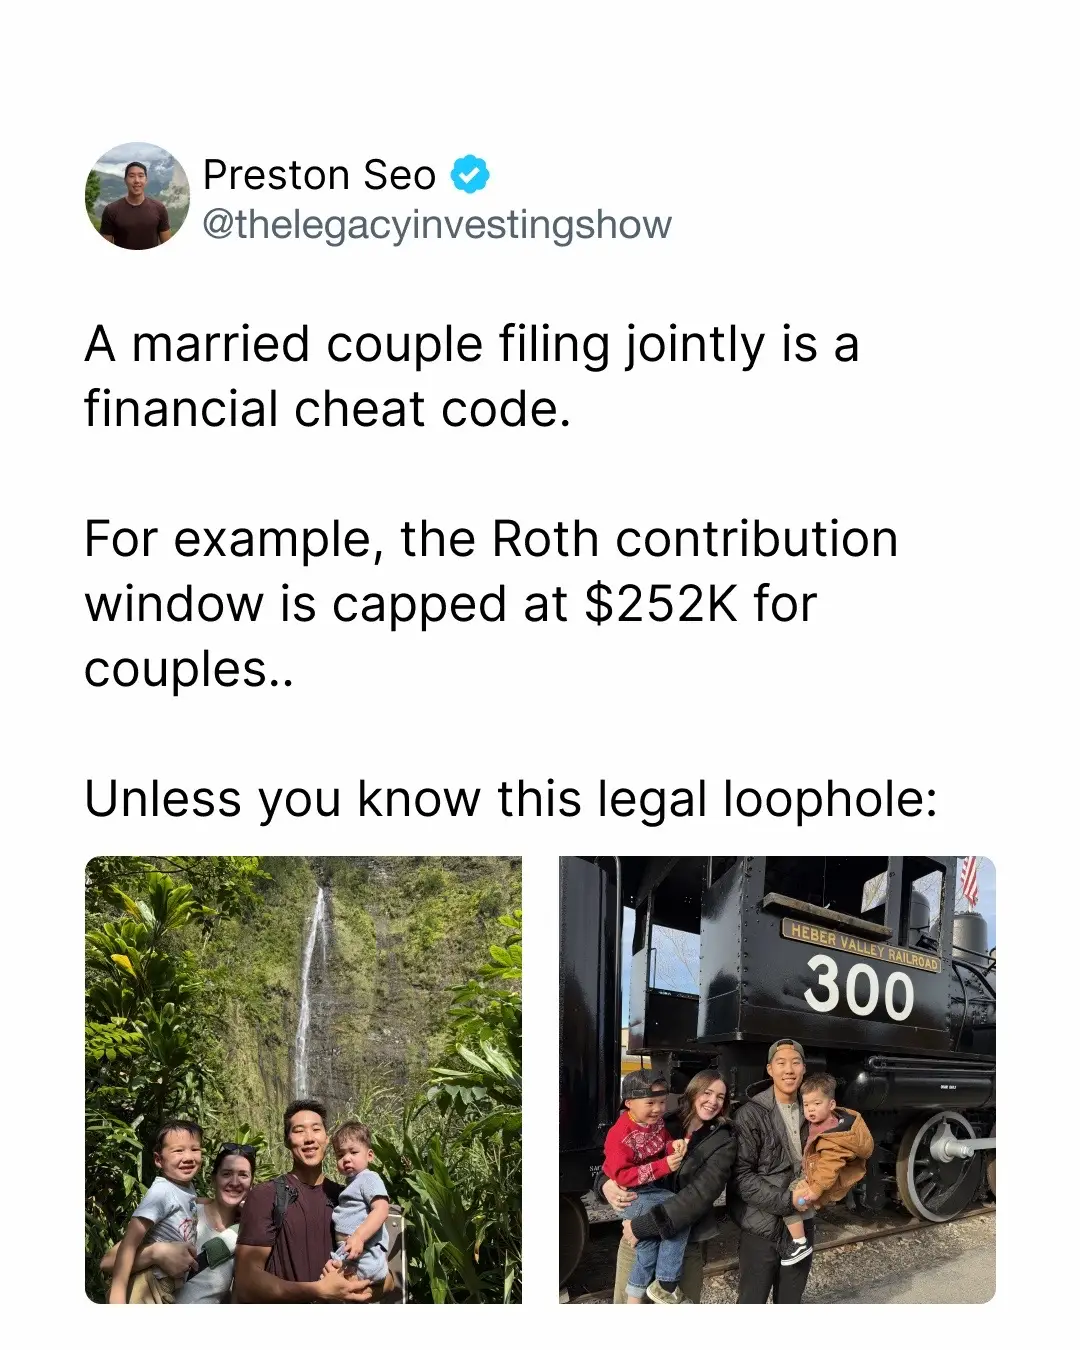
A married couple filing jointly is a financial cheat code.
@thelegacyinvestingshow
2.5M followers · usually 1.3K views a post
Views
26.6K
Likes
174
Comments
2
Shares
49
Why it worked
The post provides actionable, specific financial strategies that directly address a common pain point (high taxes) for a large audience (married couples), presented in a clear, step-by-step format that feels like valuable, exclusive information.
Summary
This post explains how married couples can leverage filing jointly to significantly reduce their tax burden. It details strategies like the Backdoor Roth IRA, increased standard deductions, favorable capital gains rates, and tax-advantaged retirement accounts, highlighting how these benefits can lead to substantial tax savings and early retirement.
Structure
- 1Introduction to filing jointly as a financial cheat code
- 2Explanation of the Backdoor Roth IRA loophole
- 3Benefits of joint filing for standard deductions and capital gains
- 4Maximizing retirement accounts (401k, HSA) for married couples
- 5Tax credits and business expense strategies for families with children
- 6Estate tax exemption for couples
- 7The problem: couples not utilizing these strategies
- 8Conclusion: the tax code favors collaboration, and most couples haven't learned the playbook
Original caption
Filing jointly isn’t just a checkbox.. it’s the most underused wealth tool in America. Most couples file a joint return and stop there. They never set up entity structure. Never run a Backdoor Roth. Never use cost segregation to offset their W2. Never build a trust. They earn $200K+ and still hand over 35% to 40% because nobody showed them what the tax code actually allows. One thing this carousel didn’t cover.. the pro-rata rule. If either spouse has pre-tax money sitting in a traditional IRA, part of your Backdoor Roth conversion gets taxed. Roll those old IRA balances into your employer’s 401(k) first. Then the backdoor is clean. Also.. the $16,100 your child can earn tax-free only avoids FICA if they’re under 18 and employed through a sole proprietorship or spousal partnership. If you run an S-Corp the payroll taxes still apply. Structure matters.
More from @thelegacyinvestingshow
More breakout videos from this creator.