Loading video…
All breakouts
246Text-HeavyOther hookEducation
Hook
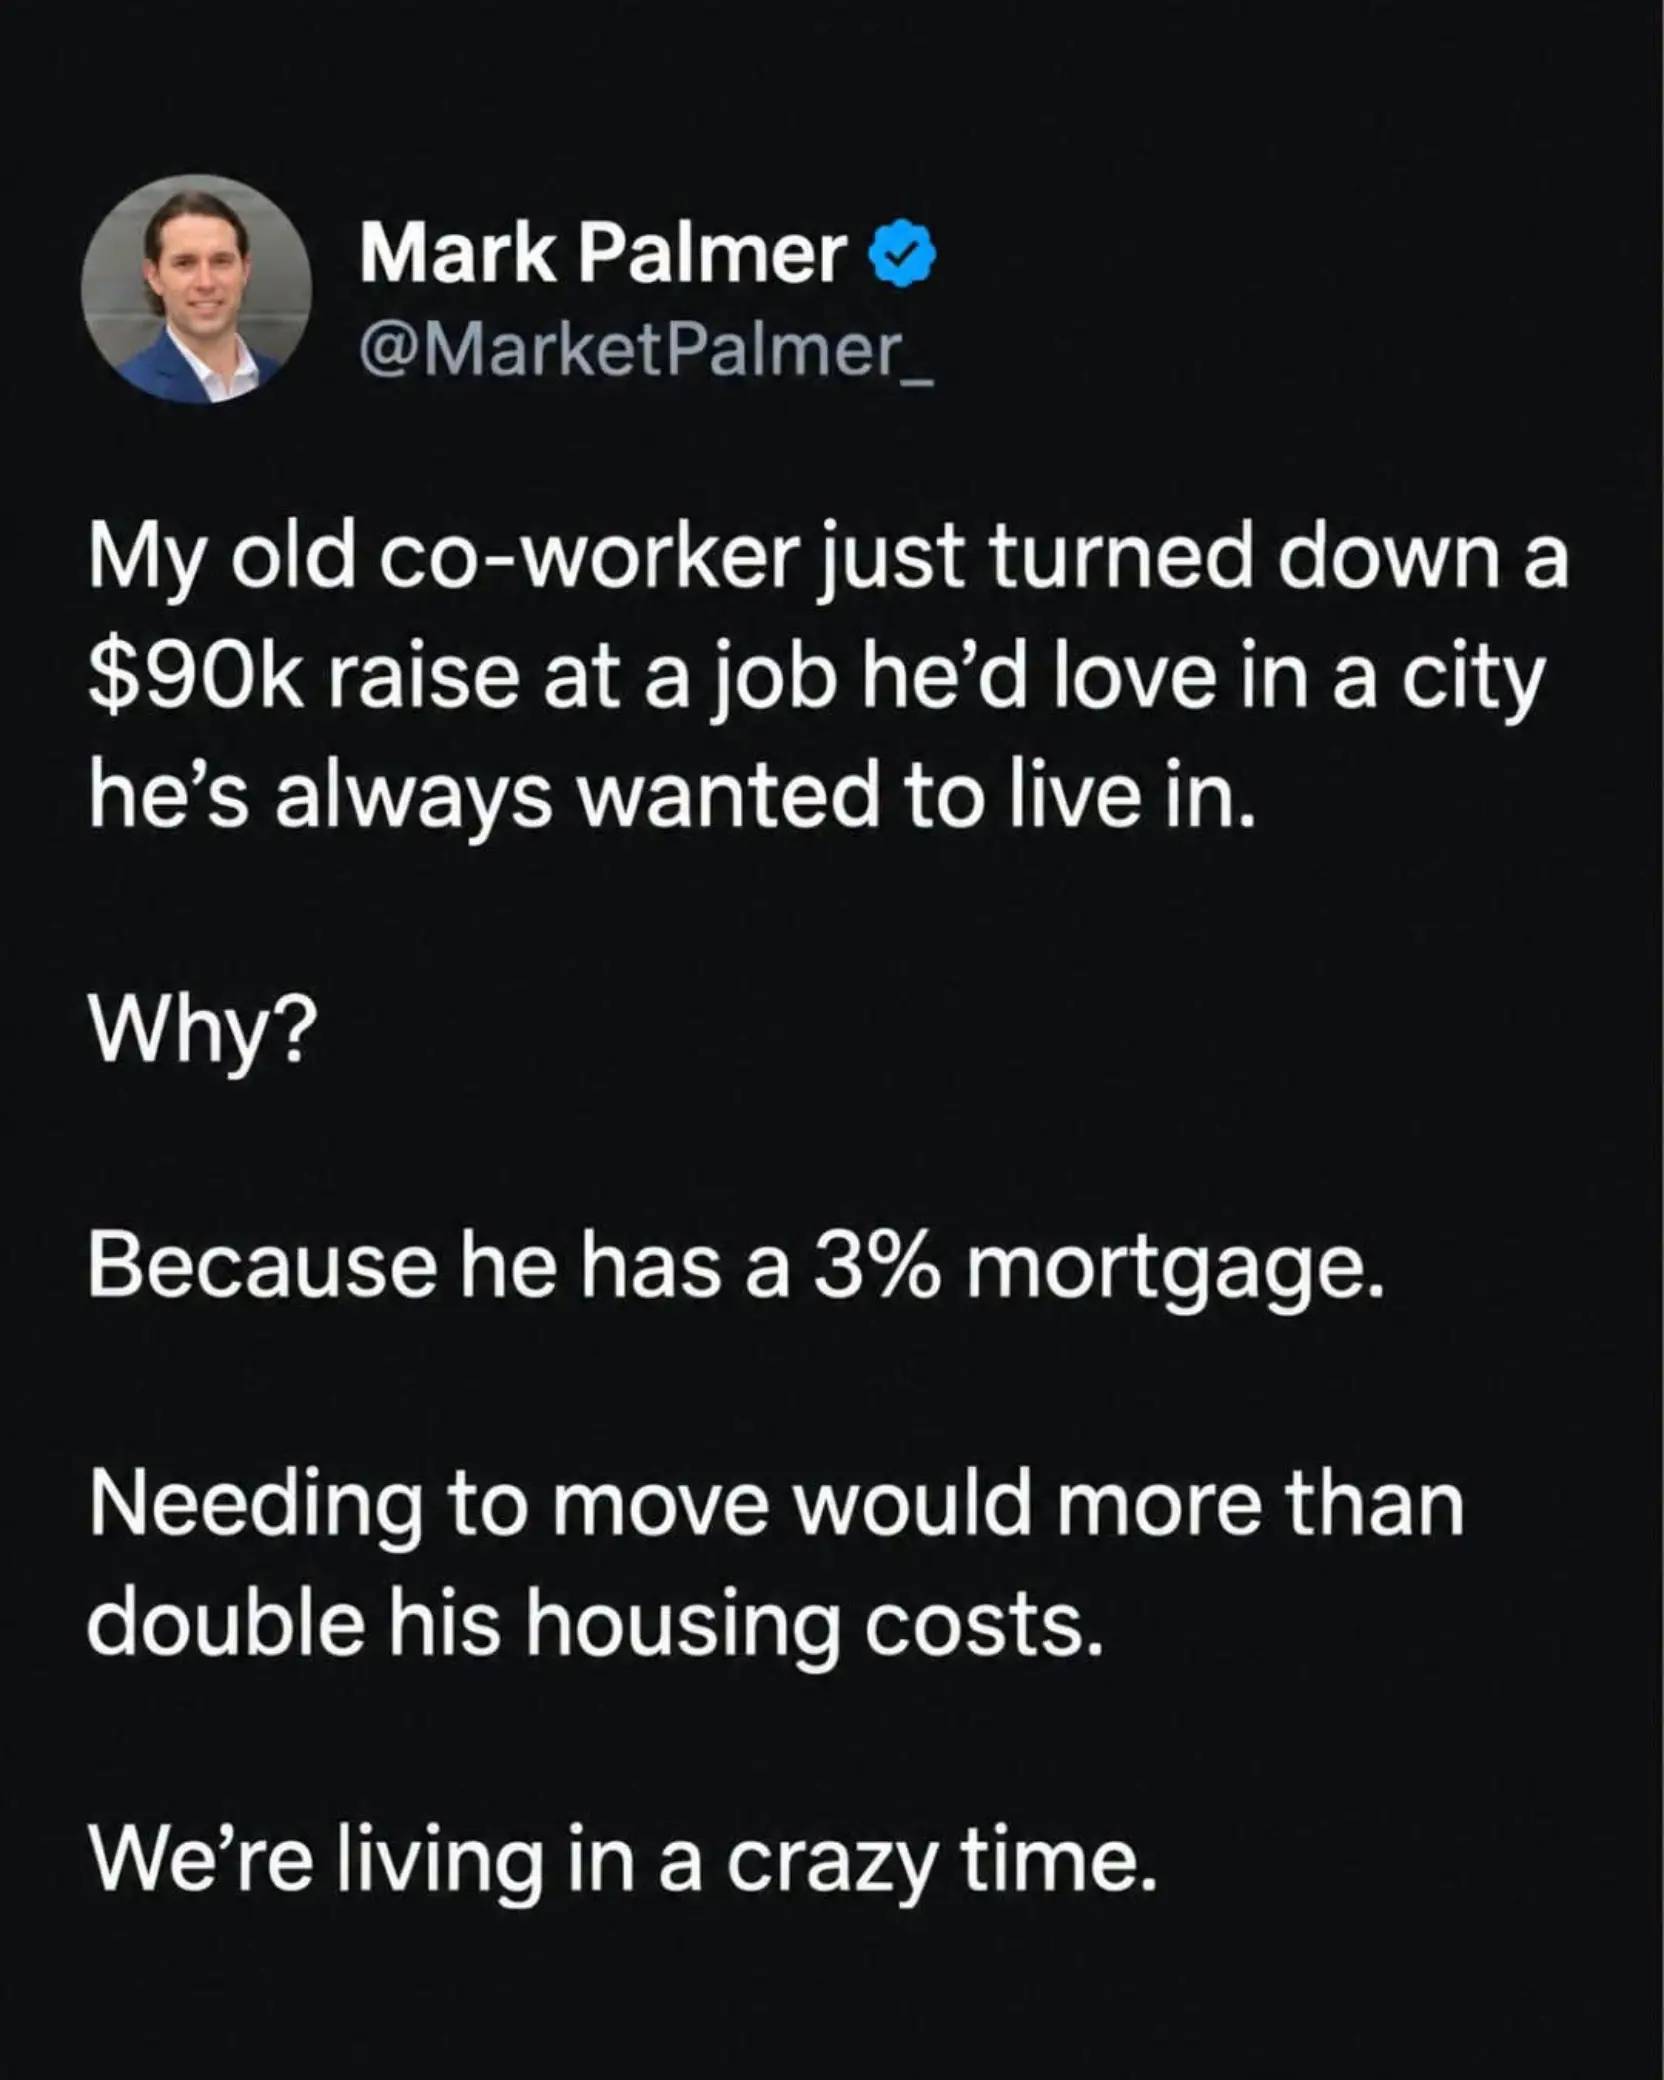
Mark Palmer @MarketPalmer_
@ethanscarellc
8.3K followers · usually 956 views a post
Views
234.8K
Likes
2.9K
Comments
301
Shares
153
Why it worked
The post taps into a widely relatable financial concern about housing costs and interest rates, using a personal anecdote to illustrate a significant economic reality in a concise and impactful way.
Summary
A social media post highlights a personal anecdote where an individual turned down a significant raise and a desired job relocation due to the financial advantage of their 3% mortgage. The post emphasizes how this low interest rate makes moving prohibitively expensive, doubling housing costs and significantly reducing the net benefit of the raise.
Structure
- 1Introduction of a co-worker's decision
- 2Reason for the decision: a 3% mortgage
- 3Financial implication: doubling housing costs
- 4Concluding thought on the current economic climate
On-screen text
Mark Palmer
@MarketPalmer_
My old co-worker just turned down a
$90k raise at a job he'd love in a city
he's always wanted to live in.
Why?
Because he has a 3% mortgage.
Needing to move would more than
double his housing costs.
We're living in a crazy time.
Original caption
A 3% mortgage in 2026 is basically a golden handcuff. 1. A 3% mortgage is a once‑in‑a‑generation asset Most people don’t realize how financially powerful a 3% fixed mortgage is. Current mortgage rates hover around 6.5–7.5%. Moving means giving up a 3% rate and replacing it with 7%. That difference can add $1,500–$3,000/month to the payment on a normal home. That’s $18K–$36K per year in extra cost — before you even factor in taxes, insurance, or moving expenses. A $90K raise suddenly shrinks fast. 2. Moving costs double because the mortgage rate doubles People think “moving costs” means boxes, trucks, deposits. But the real cost is the new mortgage. If someone bought a home at $550K, 3% interest, Payment = $2,320/month. Moving to a similar home at 7% interest, and payment = $3,650/month. That’s $1,330 more every month → $15,960/year. Over 10 years? $159,600 in extra interest. Suddenly that $90K raise is not a raise — it’s a loss. 3. The raise doesn’t beat the cost of losing the mortgage Here’s the real math: $90K raise, $16K–$36K/year extra mortgage cost, $8K–$15K moving expenses, $5K–$10K higher property taxes depending on the city, and $3K–$7K higher insurance. Net gain after moving? Often $0–$20K. That’s not a raise — that’s a lifestyle downgrade. 4. This is actually a smart financial decision Turning down a raise isn’t about fear — it’s about net gain. A 3% mortgage is an appreciating asset: It saves money every year, It protects against inflation, It increases disposable income, and It creates long‑term stability. Giving that up for a raise that doesn’t beat the math is bad economics. A 3% mortgage in 2026 is more than just a loan—it's a valuable asset. Moving means forfeiting it, and the financial loss from giving it up can completely negate any salary increase. This is precisely why individuals choose to remain in a city they love, even when presented with a significant raise.
More from @ethanscarellc
More breakout videos from this creator.